


Measuring the invisible: Insider Trading, Trading Costs, and Market Integrity
Financial markets are often described as transparent regarding price formation and stock prices, yet much of the activity that shapes prices takes place out of sight—through time delays, less transparent trading venues, and hidden informational advantages.
In his doctoral dissertation Markets in the Dark: Insider Trading and Measurement Bias, Alexander Hübbert examines how such concealed elements affect both how markets function and how they are studied and regulated.
The dissertation consists of three articles in market microstructure that analyze how trading costs are measured (Bias in Execution Cost Measures), how suspected insider trading cases move through the supervisory and judicial process (From suspected to prosecuted), and where corporate insiders choose to trade when markets are fragmented between lit and dark trading venues (Bright Light, Dark Room).
Using detailed data from the London Stock Exchange and unique confidential records from Swedish supervisory authorities, the research shows that established liquidity measures contain systematic biases, that only a small share of suspected insider trading cases lead to prosecution, and that insiders’ choice of trading venue reflects both informational advantages and legal risk.
By linking measurement methods, market surveillance, and insider behavior, Markets in the Dark demonstrates how hidden frictions in market data can influence academic research, regulatory decisions, and market integrity. The findings have important implications for how liquidity is assessed, how surveillance systems are designed, and how transparency and supervision interact in modern financial markets.
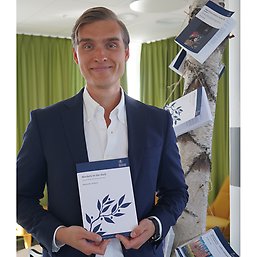
Alexander Hübbert with his thesis "Markets in the Dark: Insider Trading and Measurement Bias". Photo: Maria Stoetzer
A thread running through the thesis is that small details of market microstructure—how a trade is executed, where it is recorded, and which quote it is matched to—shape the answers to much broader questions: how costly it is to trade, how much insider trading actually happens, and whether rules are being followed. Getting these details right is a precondition for good research, good policy, and fair markets says Alexander.
Bias in Execution Cost Measures
The bid-ask spread is the most widely used measure of the cost of trading a stock. To compute it, each trade must be matched to the quote in force at the time of the trade. The standard matching rule, used since 1991, assumes the quote always arrives in the data just before the trade.
We show that this assumption is wrong in modern high-frequency data. Using London Stock Exchange data, we find that the standard rule overstates trading costs by 8 to 20 percent depending on the data feed. The bias is largest for the most liquid stocks and has grown over time. We propose a new matching method that uses each trade's footprint in the order book and eliminates the bias.
Trading costs are an input to almost every study of market quality and to every evaluation of execution by investors. Our matching method can be implemented on exchange and vendor data and gives a more accurate measure.
From suspected to prosecuted
Illegal insider trading is enforced in three steps. Brokers and exchanges report suspicious trades. The regulator decides whether to forward the report. The prosecutor decides whether to press charges. Almost all of what we know about insider trading comes from the last step, because only prosecuted cases are public.
Using proprietary data from the Swedish FSA (Finansinspektionen) and the Economic Crime Authority, I follow the full process. Only 2 percent of reported suspects are ever prosecuted. Each step screens cases on different criteria: brokers and exchanges react to market signals, the FSA weighs the suspect's connection to the firm, and the prosecutor returns focus to trading profits. Despite the low prosecution rate, suspects are, on average, trading on information. They account for almost one-fifth of the announcement-day return before the news is made public.
For this paper, the results show that prosecution data capture only a narrow slice of detected insider trading. They also highlight the central role of human investigators at brokers and exchanges. Strengthening their capacity to document the suspect's connection to the firm is what moves cases forward and could raise the share of suspected cases that are prosecuted.
Bright Light, Dark Room
Stocks do not only trade on exchanges. A large share of volume trades on dark markets, which are slower and more opaque. Corporate insiders have to choose between the two.
To trade a stock, there must be a marketplace. It can be transparent, such as an exchange where investors can see bid and ask quotes in an open order book. It can also be hidden, such as a dark pool or a broker crossing network, where the order book is not visible. This is like entering a dark room: you do not know whether someone wants to buy or sell, or even whether there is anyone there to trade with. Corporate insiders must therefore choose not only when and how much to trade, but also where to trade.
Using Swedish insider trades from 2016 to 2024, where the venue is disclosed for every trade, we find a clear pattern on the buy side. When insiders trade on information, they avoid dark markets and go to exchanges for immediacy. When insiders break rules, for example by trading during a blackout period or reporting late, they move to dark markets to hide. This choice is costly: buying on dark markets lowers the abnormal return by 6.5 percent relative to exchanges. On the sell side, trades are rarely information-driven, and we find no such pattern.
In this paper, venue choice is an additional signal for surveillance teams. A buy on a dark market during a sensitive window is more suspicious than the same buy on an exchange. For the debate on dark-market regulation, the results are reassuring in one way: informed insider purchases tend to go to exchanges, so price discovery is not obviously harmed.
Read the thesis "Markets in the Dark: Insider Trading and Measurement Bias"
Alexander Hübbert defended his doctoral thesis at Stockholm Business School on April 30.
Chair
Gustav Martinsson, Professor, Stockholm Business School (SBS), Stockholm University
Opponent
Ryan Riordan, Professor, Institute for Financial Innovation & Technology, Ludwig-Maximilians-Universität München, Germany
Examination Committee
Anders Anderson, Associate Professor, Department of Finance, Stockholm School of Economics, Stockholm, Sweden
Taylan Mavruk, Professor, Department of Business Administration, University of Gothenburg, Gothenburg, Sweden
Sara Jonsson, Professor, SBS, Stockholm University
Roine Vestman, Professor, Department of Economics, Stockholm University, (substitute)
Supervisors
Lars Nordén, Professor, SBS, Stockholm University
Björn Hagströmer, Professor, SBS, Stockholm University
Abalfazl Zareei, Associate Professor, ESCP Business School, Madrid Campus, Spain
Last updated: 2026-05-12
Source: SBS